Dragos: A 4.57x Return in a 1.75x Last-Round Exit
Insights from Fabrica Ventures Team.

Fin Exit: Only Charge Your Customers If You Make Them Happy
October 7, 2026
Wall Street seems to believe Accenture (ACN: NYSE) is in trouble. Its stock has declined significantly year-to-date, reflecting growing concerns that AI could disrupt the traditional consulting business.
So, perhaps unsurprisingly, Accenture is accelerating its M&A activity.
One of its recent acquisitions, announced in June 2026, was Dragos, at a valuation of $3.15 billion. Dragos is a cybersecurity company specializing in Operational Technology (OT) — a natural fit with Accenture’s operational capabilities — whose mission is nothing less than “Safeguarding Civilization.”
And that is not an exaggeration. Dragos protects the critical infrastructure that keeps modern society running: power grids, water systems, data centers, petrochemical plants, and other industrial facilities.
But what makes Dragos particularly interesting is the story behind its investors and customers.
Koch Industries, one of the world’s largest industrial conglomerates, could not find an adequate cybersecurity solution for its own operations. So, through its corporate venture capital (CVC) arm, Koch decided to back Dragos in its early funding rounds.
And Dragos eventually became its largest CVC investment.
Other major industrial players followed, including Aramco, National Grid, Emerson, and Rockwell Automation. Aramco eventually became Dragos’s largest customer.
This is a fascinating example of CVC working at its best: industrial companies investing in technology they greatly need, helping it develop, and becoming some of its most important customers.
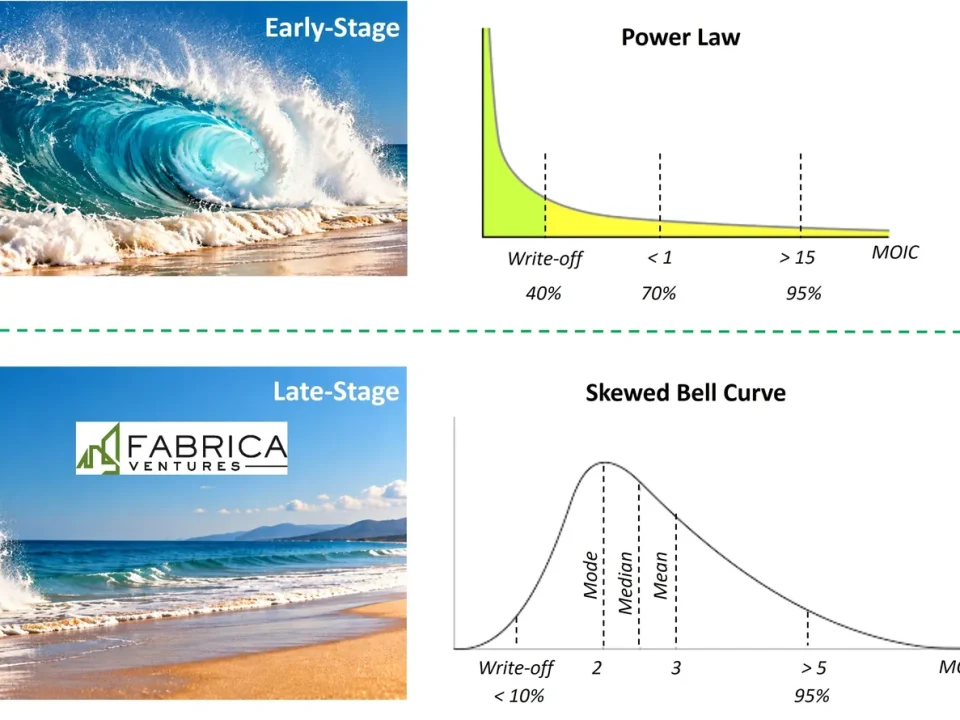
For Fabrica Ventures, Dragos has also been an exceptional late-stage investment.
Our LPs have now received the proceeds from the Dragos sale, delivering a 4.57x MoIC and an 83.0% IRR, particularly remarkable considering that Dragos’s last two funding rounds, in October 2021 and September 2023, were both at valuations of ~$1.8B – implying a gain of “just” 1.75x from those rounds.
With this exit and our other recent distributions, Fabrica Ventures Fund II’s DPI (Distributed to Paid-In Capital) has surpassed 62% in just three and a half years, placing us among the top 1% of 2023-vintage US VC funds tracked by Carta.
Conclusion
The classical SWOT framework places Opportunities and Threats in separate categories, as if they were independent forces.
But the Accenture–Dragos story illustrates something more interesting: Threats and Opportunities are not always opposites. Sometimes, threats themselves create new opportunities.